All Categories
Featured
The area integrates reasonably low energy costs, coordinated state-backed investment vehicles, and a startup ecosystem that remains less saturated than significant Western markets. Together, these aspects are beginning to form a different investment thesis for AI in the region. The rapid expansion of AI work is currently developing infrastructure obstacles worldwide.
Evaluating Cloud Platforms for the Middle EastWhile capital and hardware accessibility remain essential, energy supply and grid capability are becoming critical restraints in numerous markets. In parts of the United States and Europe, increasing energy prices, grid constraints, and regulatory approval timelines are beginning to affect how rapidly hyperscale data centres can be deployed. The Gulf area operates under various structural conditions.
Qatar, for instance, has been actively bring in hyperscale infrastructure investment, while Saudi Arabia has actually taken a more expansive method. The kingdom's Humain effort, backed by the Public Mutual fund and partnered with companies including Nvidia, AMD, AWS, Qualcomm, and Cisco, targets 1.9 gigawatts of information center capability by 2030, with longer-term aspirations of reaching 6 gigawatts by 2034.
Nevertheless, facilities investment in AI is not simply a question of capacity. Modern AI accelerators can draw close to one kilowatt of power at peak load, suggesting that the long-lasting economics of information centres depend heavily on sustained work and energy effectiveness. For financiers, this locations increasing importance on cooling innovations, energy optimisation, and the utilisation economics of inference work instead of just headline capability figures.
This is where the GCC may hold an advantage that is frequently neglected in international AI conversations., for example, prioritises the adoption of AI across several government departments and sectors.
Key AI Computing Trends in the GCC
Solutions built for these environments require specialised understanding of local regulative and monetary systems that worldwide startups might find tough to reproduce rapidly. AI tools that transform clinicians' voice recordings into Arabic-language medical documents, or systems developed to automate regulatory compliance for GCC-specific structures, fix highly useful operational problems.
From a financial investment perspective, start-ups operating in these specialised sections often deal with less competitors than similar business in the United States or Europe. Many of the technologies established for Arabic-language environments or region-specific regulative systems may also find demand in underserved markets throughout Africa and parts of Central Asia, where similar linguistic and regulative conditions exist.
First, infrastructure investments ought to be evaluated not only by announced data centre capability but also by energy efficiency, utilisation rates, and long-term workload sustainability. Second, a few of the most resistant AI businesses may emerge from business embedded in operational workflows instead of consumer-facing applications. Enterprise software that quietly automates compliance, documents, logistics optimisation, or financial analysis often creates stable, recurring revenue because organisations depend on it for daily operations.
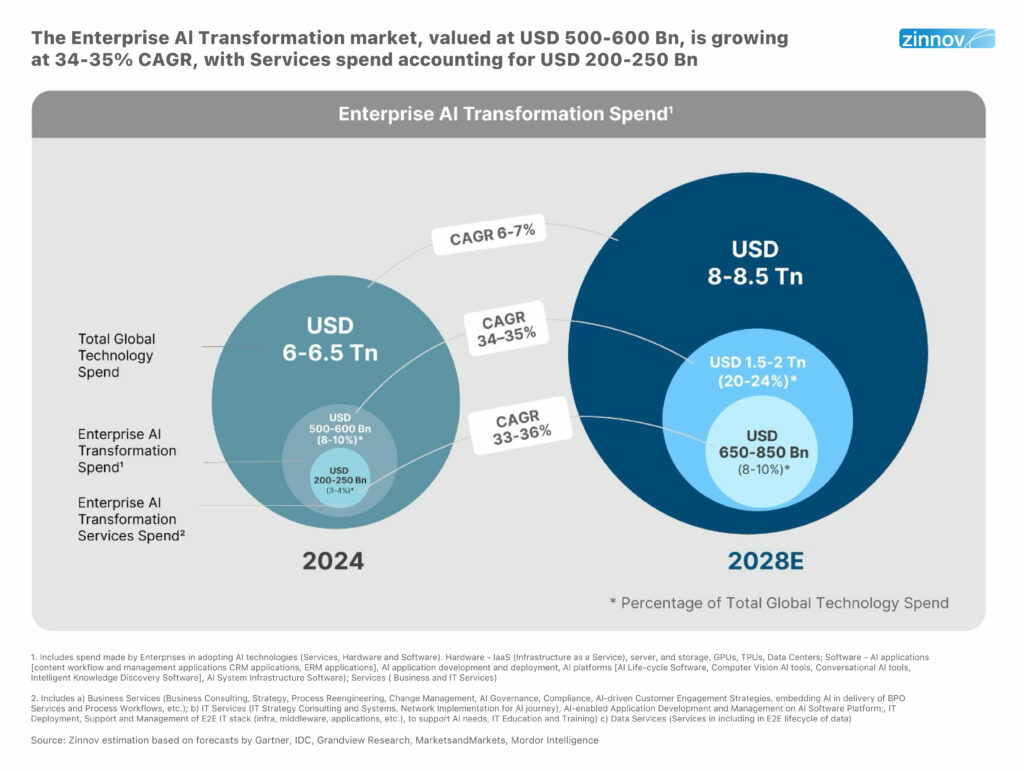
As language models, speech acknowledgment systems, and enterprise AI tools become more customized to Arabic-speaking markets, the business constructing these capabilities might ultimately serve a much wider location where similar linguistic barriers exist. As local data centre infrastructure expands and business adoption of AI relocations from pilot tasks to large-scale procurement, the Gulf's position in the international AI ecosystem might start to evolve.
Key Benefits of Applied AI Innovation
The structural conditions that enable this shift are already emerging: access to energy resources, coordinated capital release through sovereign funds, and a regulative environment where federal governments are actively encouraging AI adoption. The concern for financiers is less whether these conditions exist and more how rapidly capital and founders relocate to construct within them before the chance ends up being extensively identified.
Evaluating Cloud Platforms for the Middle EastAs 2025 wanes, the Gulf Cooperation Council's technology and startup environment has actually reached an inflection point that fundamentally modifies its trajectory. Venture financial investment activity reached record levels this year, yet the distribution of capital informs a more complicated story than aggregate numbers recommend. Capital is no longer streaming broadly throughout the environment; it is focusing in less, larger, and structurally fully grown companies (Source 1: Primary Information).
Business like Tabby, Tamara, and Sallafintech and e-commerce platforms that have matured into unicorn statuscaptured disproportionate shares of readily available capital. This concentration signals that the GCC ecosystem is "maturing" rapidly, transitioning from a landscape of seed-stage experiments to one controlled by structural debt consolidation and capital performance requireds. The year 2026 will be defined by discipline.

Latest Posts
Recent GCC Tech Innovation Trends
The Best Workflow Tools Analyses in 2026
New Venture Updates From the GCC Startup Sector