All Categories
Featured
Main Advantages of Applied AI Roadmaps
Table of Contents
Startups that can demonstrate exclusive information partnerships with big enterprises will command assessment premiums.-- The expansion of international AI companies into the GCC, integrated with large business AI release, develops unprecedented demand for specialized talent. The supply of qualified AI engineers, data scientists, and artificial intelligence scientists can not fulfill present need, developing wage inflation that improves the whole startup expense structure.
Worldwide AI laboratories provide compensation bundles that include equity in high-growth worldwide companies, making it impossible for local start-ups to complete on total compensation. Second, business provide stability and advantages that start-ups can not match. Third, the swimming pool of in your area trained AI talent stays small regardless of federal government financial investments in education.
The most effective GCC start-ups in 2026 will be those that can construct AI systems that require less, more specialized human operatorsessentially, automating the automation itself (Source 8: Labor Market Data).-- Federal government procurement will operate as the primary need motorist for innovation start-ups in the GCC for the foreseeable future.
The procurement dynamic develops a particular set of incentives for start-ups. Companies that secure federal government contracts gain income stability and trustworthiness that personal customers worth. However, federal government procurement timelines are long, payment cycles are extended, and compliance requirements are challenging. Startups that end up being based on government agreements face margin compression and strategic inflexibility.
Main Benefits of Applied Digital Innovation
A single federal government deployment can work as a recommendation case that verifies a start-up's technology for international purchasers. This technique needs startups to develop products that are versatile to multiple contexts, instead of custom-made options for single federal government customers (Source 9: Procurement Analysis).-- The regulative environment across GCC member states is diverging even as the region pursues financial combination.
Each jurisdiction is trying to develop a regulatory environment that draws in specific types of technology business. Qatar's regulation focuses on niche sectors like sports innovation and education. For startups, regulatory divergence creates both challenges and chances.
However, the compliance expenses of multi-market operations are significant and favor larger, better-capitalized business (Source 10: Regulative Analysis).-- The GCC's investments in physical and digital infrastructure are developing structural benefits that will intensify in 2026. Data center capability, fiber optic networks, and energy infrastructure are requirements for AI development, and the GCC has these properties in amounts that many global markets can not match.
-- The convergence of these ten forces will produce specific, observable outcomes in 2026: will reach $500 million-$1 billion in transaction value as early endeavor funds seek liquidity.
The GCC innovation environment is transitioning from a capital-rich experimenter to a disciplined, synthetic market. The age of easy money and quick scaling without structural maturity is ending.
Are Middle Eastern Enterprises Ready for Applied AI?
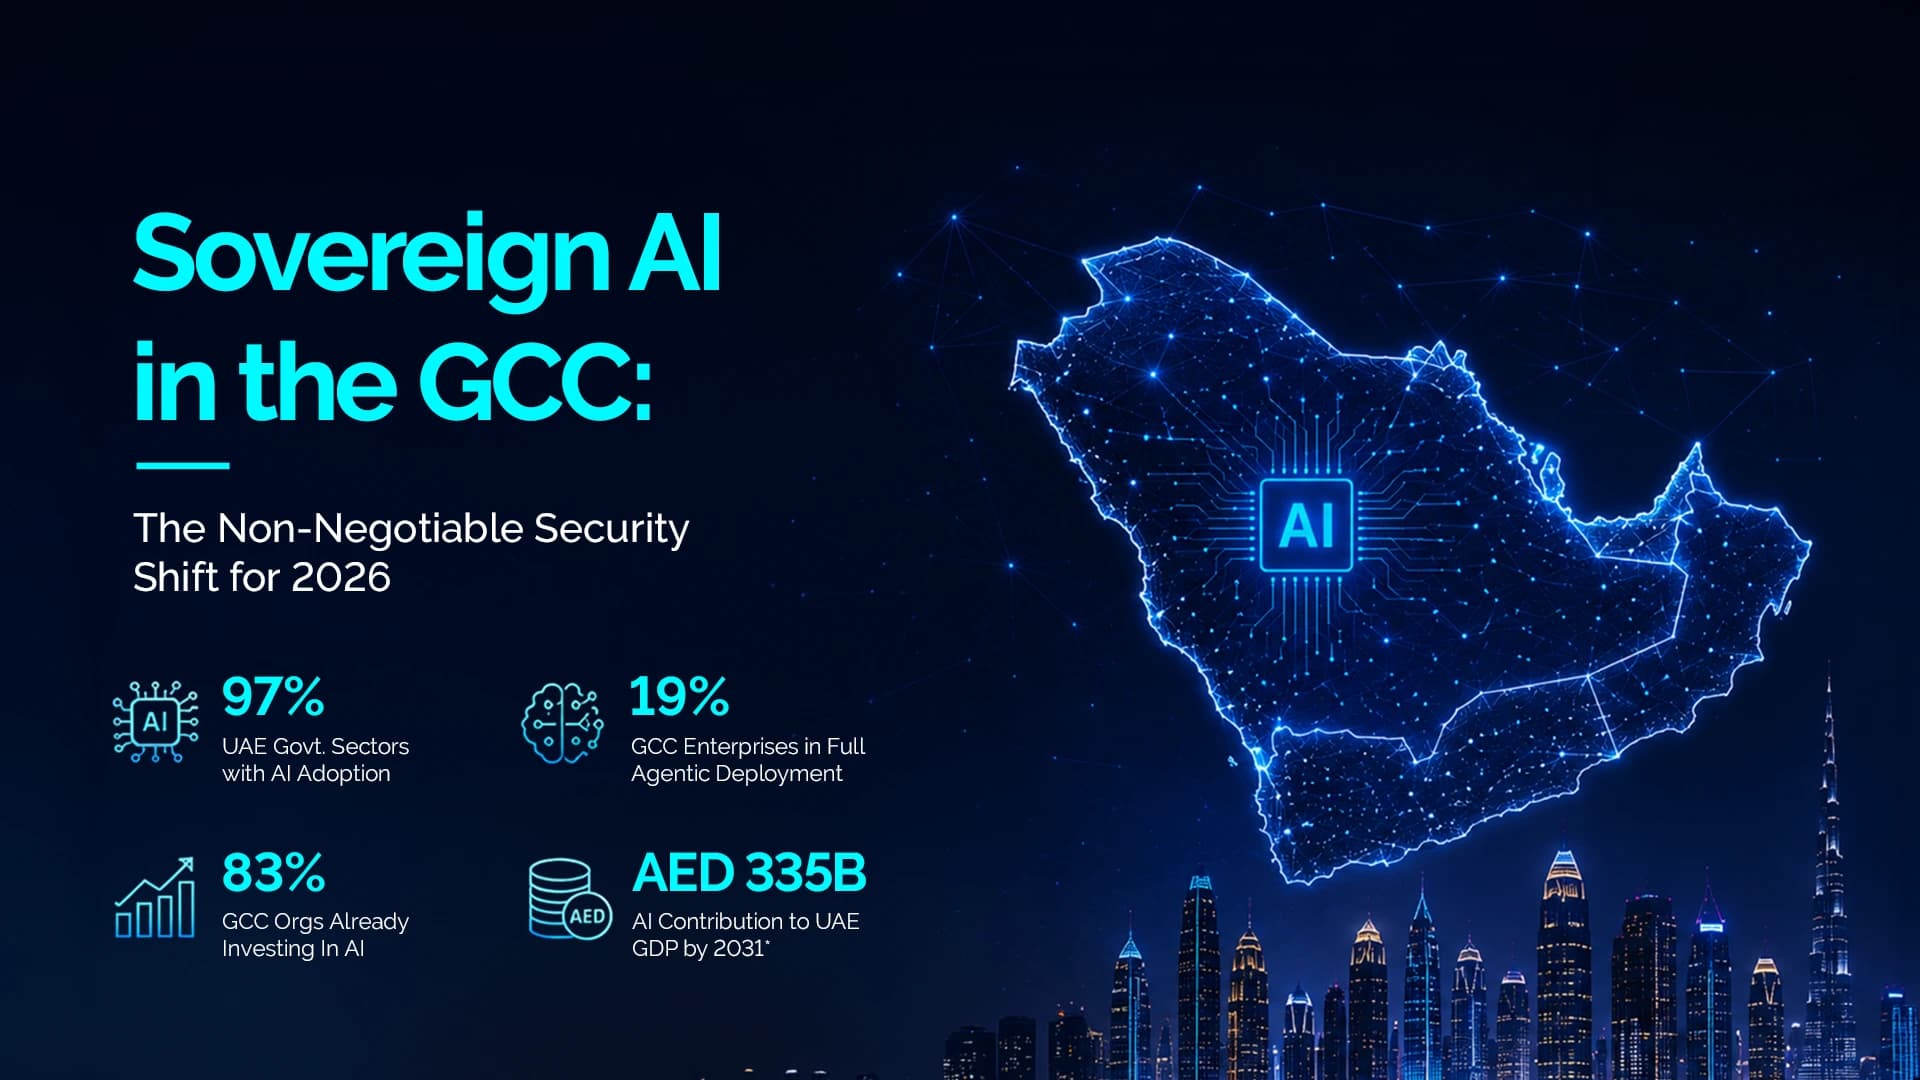
The worldwide financial landscape of late 2025 is seeing a definitive shift. While Western capital markets face liquidity restrictions, the Gulf Cooperation Council (GCC) has actually emerged as the undisputed architect of the post-oil digital economy. We are witnessing the age of "Sovereign Venture Commercialism"a design where hydrocarbons serve as the liquidity engine for a quick, state-directed shift into high-technology industrialization, artificial intelligence, and advanced monetary systems.
In the very first half of 2025 alone, MENA start-up financial investment hit, marking a staggering.1 This rise is defined by multi-billion dollar commitments that indicate a departure from passive property accumulation to active environment building. Saudi Arabia's Public Mutual fund (PIF) is managing a $100 billion industrial push through, while the UAE seals its "Falcon Economy" status with a projected by 2029.2 All at once, Qatar has strongly released almost half of its $1 billion "Fund of Funds," bring in Silicon Valley's elite to Doha.
-- The convergence of these ten forces will produce specific, observable outcomes in 2026: will reach $500 million-$1 billion in deal worth as early endeavor funds seek liquidity.
The GCC technology ecosystem is transitioning from a capital-rich experimenter to a disciplined, synthetic market. The period of simple money and quick scaling without structural maturity is ending.
The international financial landscape of late 2025 is witnessing a conclusive shift. While Western capital markets face liquidity restrictions, the Gulf Cooperation Council (GCC) has actually emerged as the indisputable designer of the post-oil digital economy. We are experiencing the age of "Sovereign Venture Capitalism"a design where hydrocarbons serve as the liquidity engine for a quick, state-directed transition into high-technology industrialization, synthetic intelligence, and advanced financial systems.
Evaluating 2026 Software Frameworks and Tools
In the very first half of 2025 alone, MENA startup financial investment hit, marking an incredible.1 This surge is specified by multi-billion dollar commitments that indicate a departure from passive possession accumulation to active environment building. Saudi Arabia's Public Mutual fund (PIF) is orchestrating a $100 billion industrial push through, while the UAE seals its "Falcon Economy" status with a forecasted by 2029.2 Simultaneously, Qatar has actually strongly deployed nearly half of its $1 billion "Fund of Funds," drawing in Silicon Valley's elite to Doha.

Latest Posts
Recent GCC Tech Innovation Trends
The Best Workflow Tools Analyses in 2026
New Venture Updates From the GCC Startup Sector