All Categories
Featured
Key AI Development Trends in Regional Markets
Table of Contents
Traditional fintech and e-commerce platforms like Tabby are now retrofitting AI-native layers onto their existing architectures. This upgrade cycle develops assessment benefits that intensify gradually. The differentiation in between "AI-native" and "AI-enabled" startups will end up being the primary filter for institutional financiers evaluating GCC opportunities in 2026. Fadi Ghandour's implicit critique of the region's start-up environment brings analytical weight: the next unicorns should be constructed on AI automation, not market arbitrage.
AI-adjacent infrastructure companies brought in the biggest rounds, while consumer-facing platforms without proprietary technology components saw extended fundraising timelines and lower valuations.-- Secondary transactions will become necessary as venture funds method later phases and startup evaluations increase.
The hidden reasoning is counterproductive: secondary markets alter the "exit-only" mindset that has controlled GCC startup culture. Creators can now sell partial stakes without triggering an IPO, allowing them to preserve functional control while supplying liquidity to early financiers and employees. This mechanism produces a more mature capital environment where companies can stay personal longer while still rewarding early capital providers.
Both jurisdictions need secondary liquidity facilities to attract global family workplaces and institutional investors who require flexible exit mechanisms (Source 3: Market Structure Analysis). The development of devoted secondary trading platforms, or the combination of secondary abilities into existing exchanges, will be a defining facilities story of 2026. For endeavor funds approaching their maturity horizons, secondary markets represent the difference in between returning capital to limited partners on schedule versus looking for extensions.
-- International AI labs are establishing irreversible operations in Abu Dhabi and Riyadh, drawn by 2 elements that the GCC possesses in abundance: capital and energy facilities. Large language design training needs both funds and industrial-scale computing power, making the Gulf's sovereign wealth funds and energy properties distinctively attractive to AI designers.
Proven Tips for Successful Cloud Adoption
Unlike previous waves of Chinese tech expansion that focused on consumer hardware and e-commerce, the existing expansion targets AI infrastructure, cloud computing, and smart city contracts. Mid-tier Chinese AI firms, constrained by domestic competitors and global sanctions, see the GCC as a neutral market where they can deploy technology without geopolitical friction.
Global AI business developing Gulf operations create talent pipelines and knowledge transfer systems that local environments can not reproduce naturally. They also consolidate the GCC's position as a third pole in the worldwide AI landscape, distinct from Silicon Valley and Beijing (Source 4: Geopolitical Analysis). For regional startups, this colonization provides both chances and threats.
-- Saudi Arabia and the UAE's capital markets are participated in direct competition to become the region's favored exit route for innovation companies. This competition, while beneficial for startups in the short-term, creates tactical complexity for companies preparing IPOs. Saudi Arabia's Capital Market Authority has implemented reforms developed to lower listing timelines and disclosure requirements for technology business.
How GCC Digital Startups Lead 2026 Innovation
IPO preparedness has actually become a strategic concern in both jurisdictions. Unicorns Tabby, Tamara, and Salla are placed to check public markets in 2026, and their efficiency will set precedents for the entire ecosystem. If these companies attain strong public market debuts, they will confirm the GCC's capability to support big technology listings.
The competitors encompasses secondary listings and dual-listing structures. Business are increasingly structuring their corporate entities to preserve optionality between Saudi and UAE exchanges, a flexibility that includes legal and administrative intricacy but takes full advantage of tactical alternatives.-- AI automation will disproportionately impact junior functions including experts, coordinators, customer assistance, and fundamental coding functions.
Federal governments throughout the GCC sped up adoption of AI as fundamental facilities in 2025, recognizing that automation is not optional however essential for preserving international competitiveness. This acceleration develops a tension between short-term work objectives and long-lasting efficiency imperatives.
Key Benefits of Applied AI RoadmapsStage three, noticeable on a 3-5 year horizon, will include fundamental restructuring of organizational hierarchies as AI minimizes the requirement for middle management layers (Source 6: Labor Economics Analysis). Universities and schools in the GCC face existential pressure to transform their curricula. The conventional model of understanding transmissionlectures, memorization, standardized testingis ending up being outdated as AI systems can perform these functions more effectively.
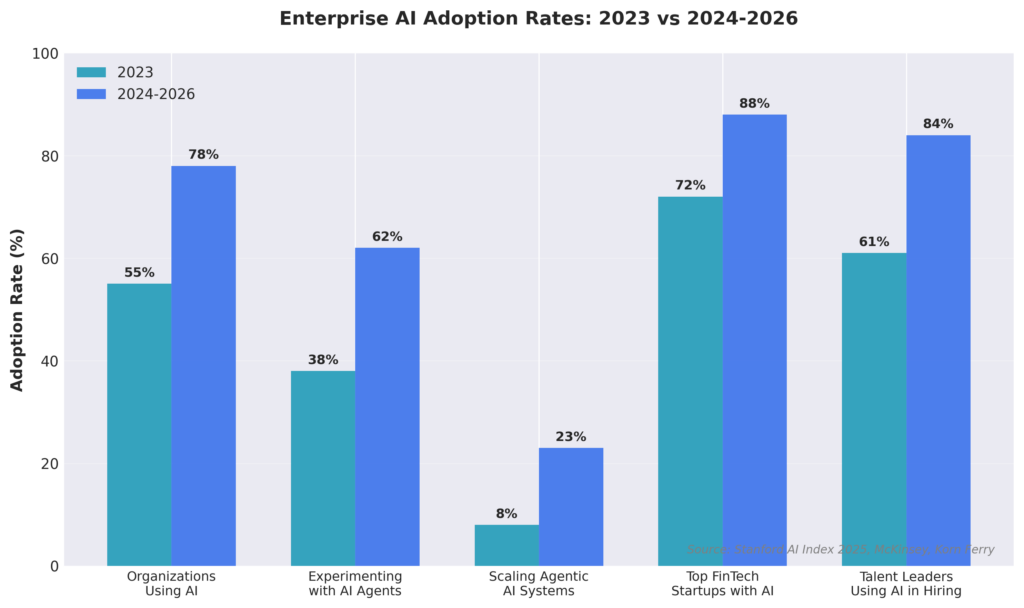
-- Large business in the GCC are transitioning from AI experimentation to major implementation. This shift alters the demand characteristics for innovation startups, which now find themselves completing versus internal development teams at sovereign wealth funds, oil business, and government entities. The enterprise implementation wave develops a bifurcation in the startup community.

Latest Posts
Recent GCC Tech Innovation Trends
The Best Workflow Tools Analyses in 2026
New Venture Updates From the GCC Startup Sector