All Categories
Featured
High-Impact IT Roadmaps for 2026 Firms
Table of Contents
The region integrates reasonably low energy expenses, collaborated state-backed investment automobiles, and a startup environment that stays less saturated than significant Western markets. Together, these aspects are beginning to form a various investment thesis for AI in the area. The rapid expansion of AI workloads is currently producing facilities challenges worldwide.
While capital and hardware schedule remain essential, energy supply and grid capability are emerging as vital restraints in many markets. In parts of the United States and Europe, increasing energy rates, grid limitations, and regulative approval timelines are beginning to affect how quickly hyperscale data centres can be released. The Gulf region operates under different structural conditions.
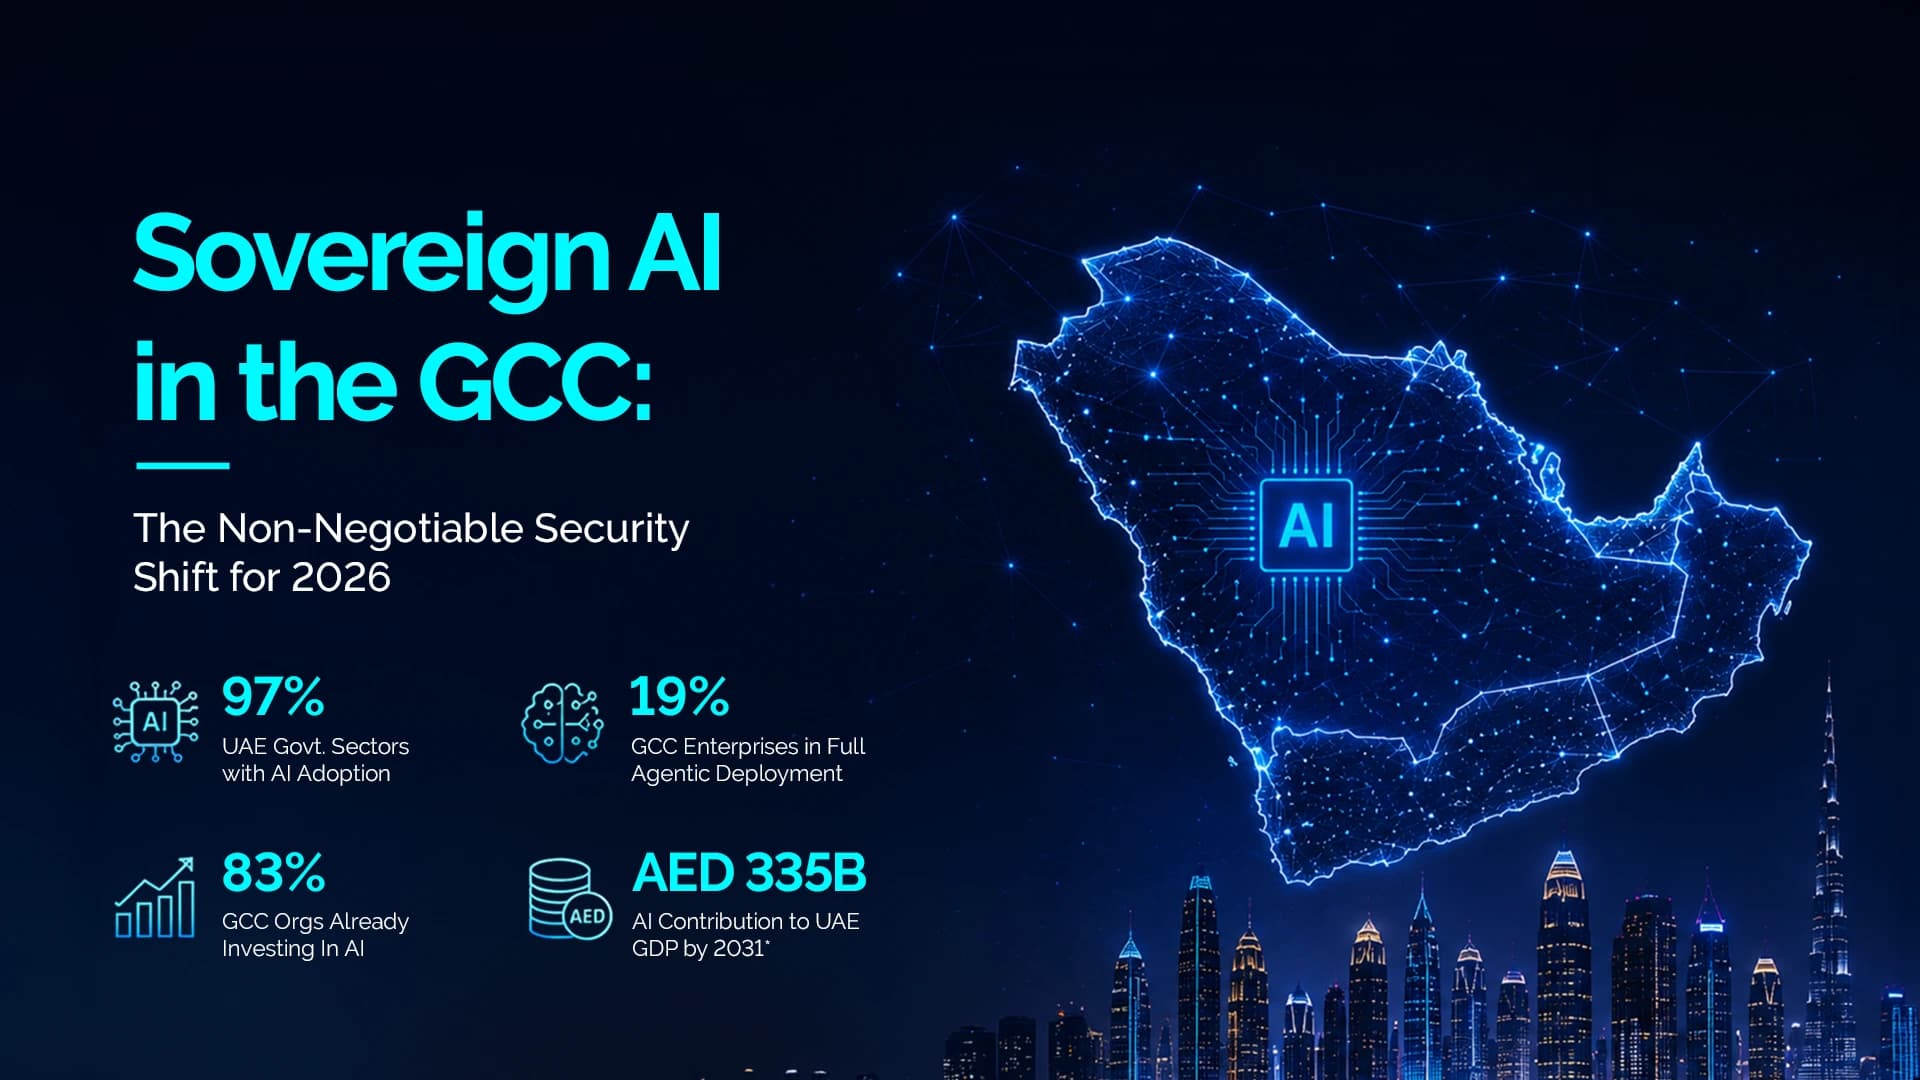
Qatar, for example, has actually been actively bring in hyperscale facilities investment, while Saudi Arabia has actually taken a more extensive technique. The kingdom's Humain initiative, backed by the Public Mutual fund and partnered with companies consisting of Nvidia, AMD, AWS, Qualcomm, and Cisco, targets 1.9 gigawatts of information center capability by 2030, with longer-term ambitions of reaching 6 gigawatts by 2034.
Infrastructure investment in AI is not simply a question of capacity. Modern AI accelerators can draw close to one kilowatt of power at peak load, suggesting that the long-lasting economics of data centres depend heavily on continual workloads and energy effectiveness. For financiers, this locations increasing significance on cooling technologies, energy optimisation, and the utilisation economics of inference work instead of just heading capability figures.
This is where the GCC may hold a benefit that is often ignored in worldwide AI conversations., for example, prioritises the adoption of AI across multiple government departments and sectors.
The Evolution of Digital Growth for Enterprises
Solutions built for these environments need specialised understanding of regional regulatory and monetary systems that global start-ups may find tough to duplicate rapidly. AI tools that transform clinicians' voice recordings into Arabic-language medical documents, or systems designed to automate regulatory compliance for GCC-specific structures, resolve extremely practical functional issues.
From an investment point of view, start-ups operating in these specialised sections often face less competitors than equivalent business in the United States or Europe. Much of the innovations developed for Arabic-language environments or region-specific regulatory systems may likewise find demand in underserved markets across Africa and parts of Central Asia, where similar linguistic and regulatory conditions exist.
Initially, infrastructure investments must be examined not only by revealed data centre capacity but also by energy effectiveness, utilisation rates, and long-lasting workload sustainability. Second, a few of the most resistant AI services may emerge from companies embedded in functional workflows instead of consumer-facing applications. Enterprise software that quietly automates compliance, documents, logistics optimisation, or financial analysis typically creates steady, repeating income due to the fact that organisations depend on it for everyday operations.
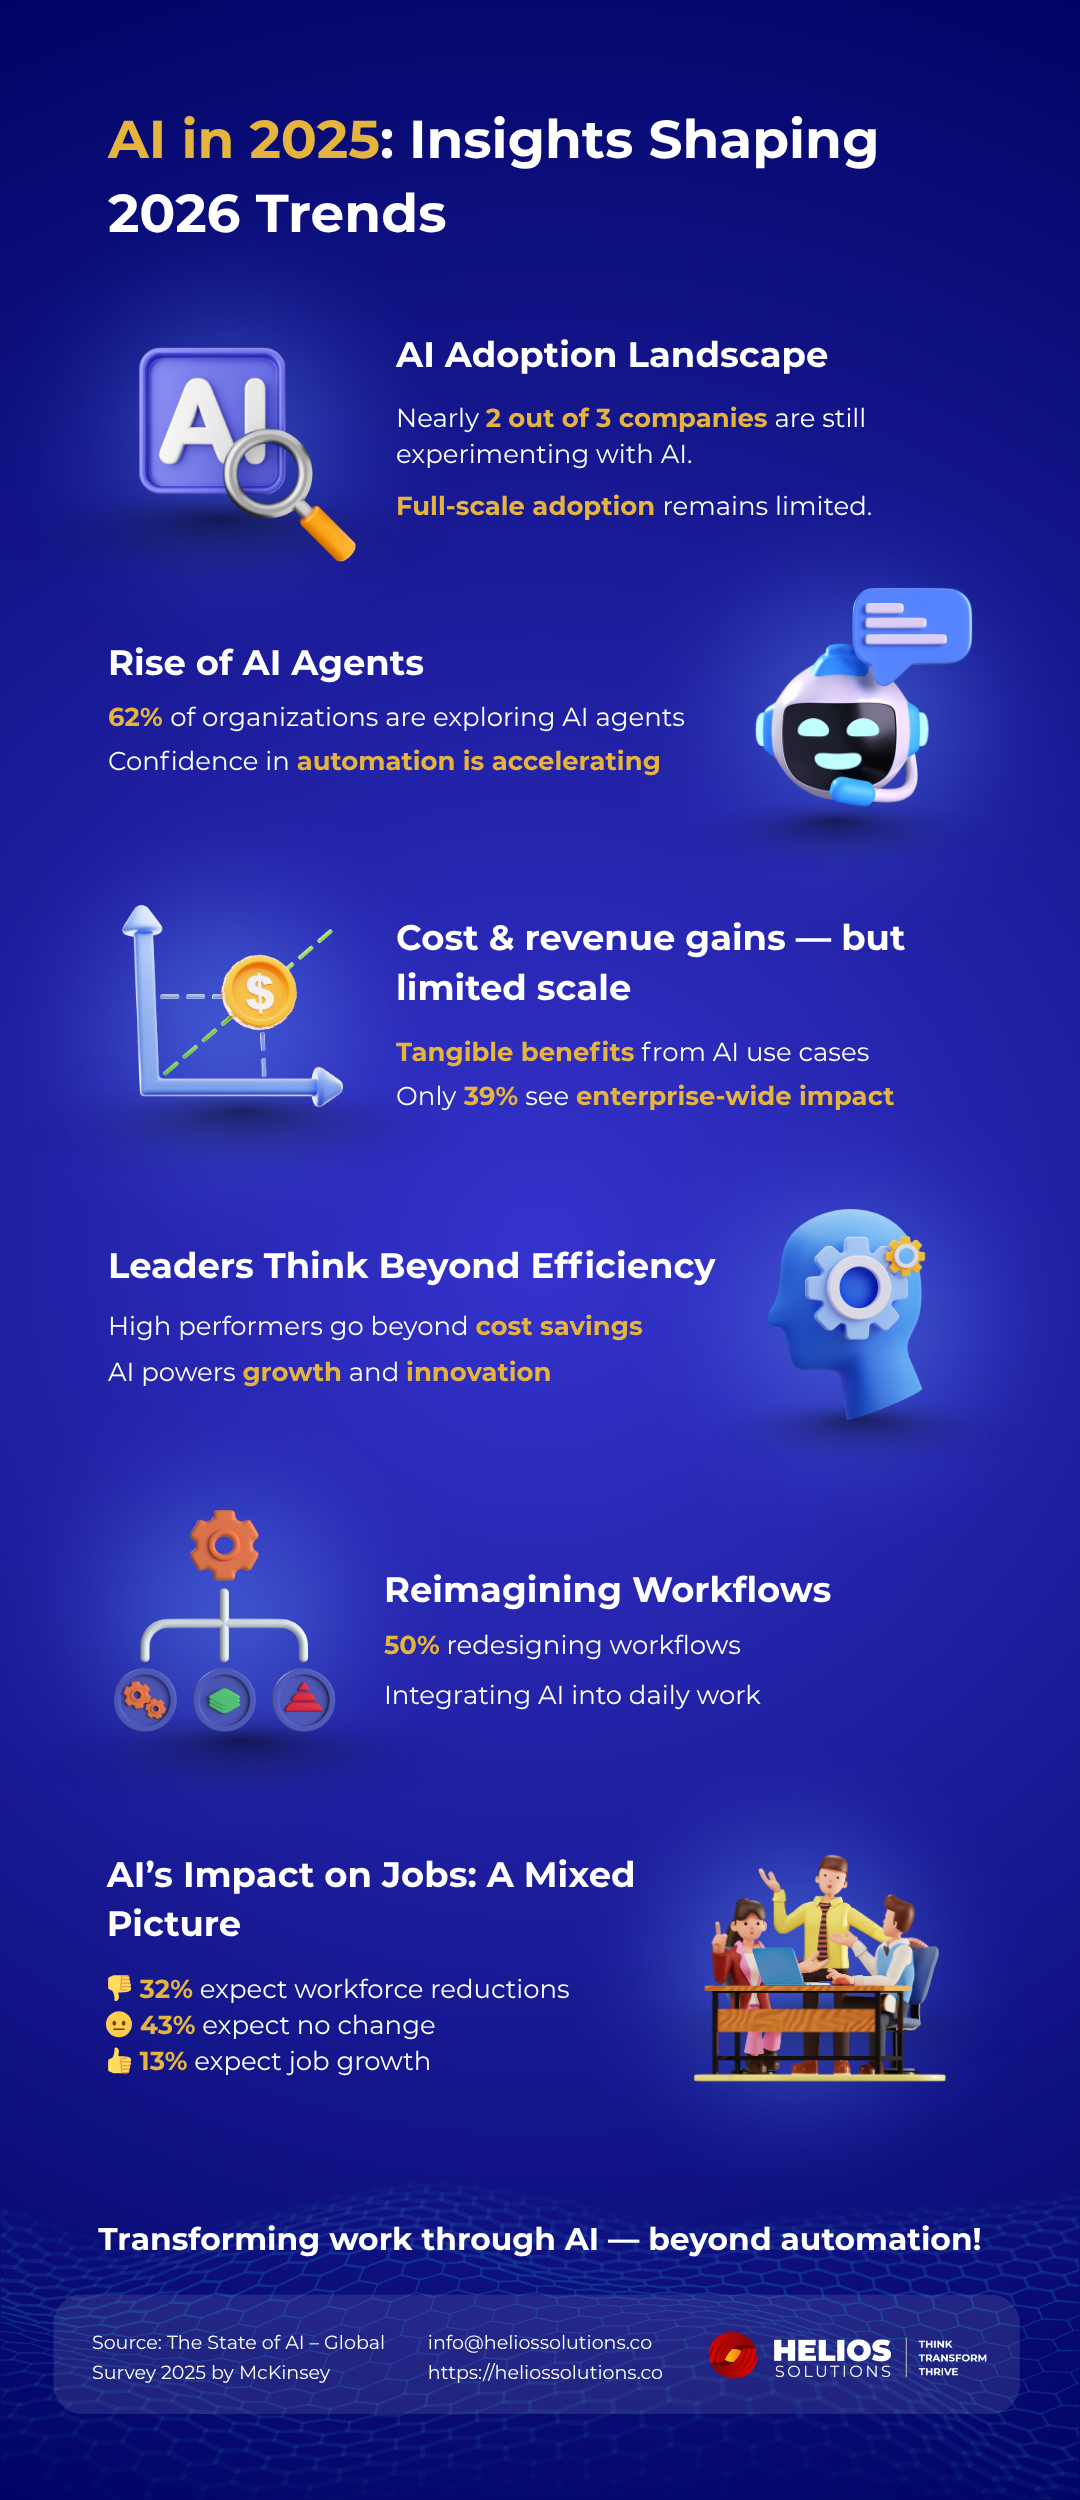
As language models, speech recognition systems, and business AI tools become more tailored to Arabic-speaking markets, the business building these abilities might ultimately serve a much wider location where comparable linguistic barriers exist. As regional information centre facilities broadens and business adoption of AI relocations from pilot projects to massive procurement, the Gulf's position in the global AI ecosystem may start to develop.
How to Leverage AI for Maximum Digital Impact
The structural conditions that enable this shift are currently emerging: access to energy resources, collaborated capital release through sovereign funds, and a regulative environment where federal governments are actively motivating AI adoption. The concern for financiers is less whether these conditions exist and more how rapidly capital and creators move to construct within them before the chance ends up being extensively identified.
As 2025 wanes, the Gulf Cooperation Council's innovation and startup environment has reached an inflection point that basically changes its trajectory. Venture investment activity reached record levels this year, yet the circulation of capital informs a more complex story than aggregate numbers recommend. Capital is no longer streaming broadly throughout the environment; it is concentrating in fewer, bigger, and structurally fully grown business (Source 1: Main Information).
Business like Tabby, Tamara, and Sallafintech and e-commerce platforms that have matured into unicorn statuscaptured out of proportion shares of available capital. This concentration signals that the GCC ecosystem is "maturing" quickly, transitioning from a landscape of seed-stage experiments to one dominated by structural consolidation and capital effectiveness mandates. The year 2026 will be defined by discipline.

Latest Posts
Recent GCC Tech Innovation Trends
The Best Workflow Tools Analyses in 2026
New Venture Updates From the GCC Startup Sector