All Categories
Featured
Table of Contents
Traditional fintech and e-commerce platforms like Tabby are now retrofitting AI-native layers onto their existing architectures. This upgrade cycle creates evaluation advantages that compound in time. The differentiation between "AI-native" and "AI-enabled" start-ups will become the main filter for institutional investors examining GCC opportunities in 2026. Fadi Ghandour's implicit review of the region's start-up community carries analytical weight: the next unicorns need to be developed on AI automation, not market arbitrage.
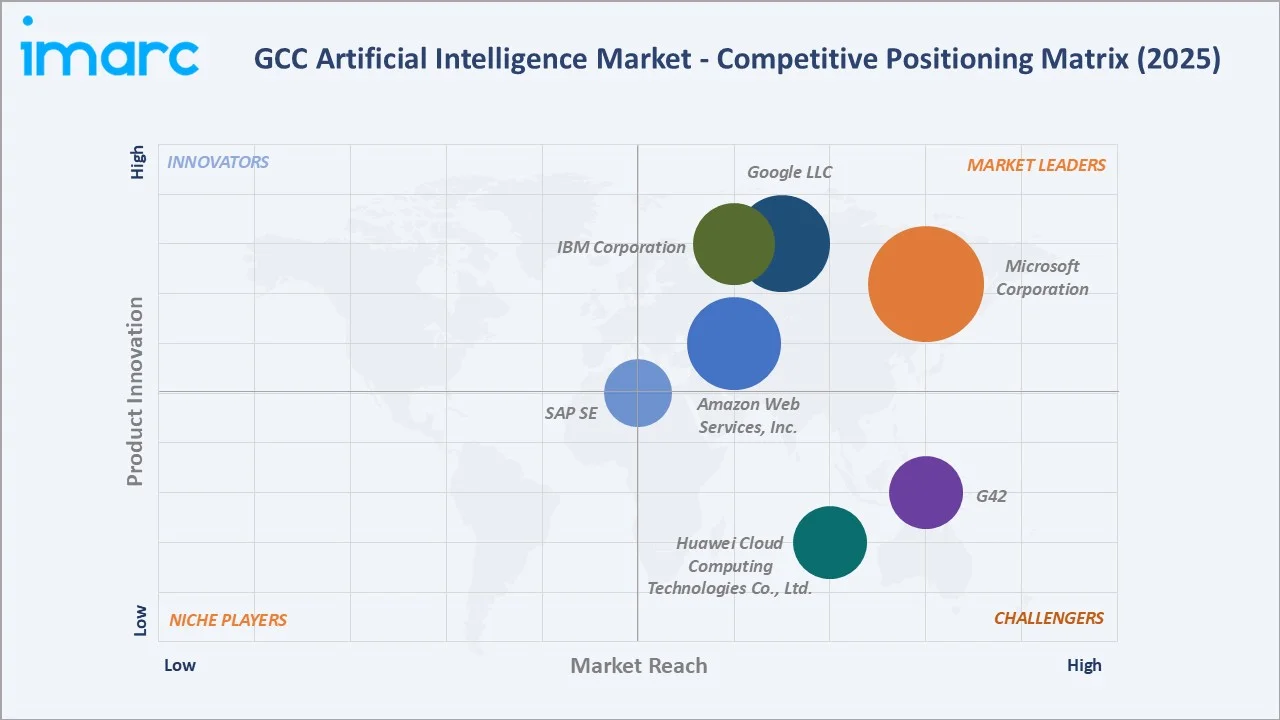
AI-adjacent facilities companies brought in the biggest rounds, while consumer-facing platforms without proprietary technology elements saw extended fundraising timelines and lower assessments.-- Secondary transactions will end up being necessary as endeavor funds method later stages and start-up evaluations increase.
The hidden reasoning is counterproductive: secondary markets alter the "exit-only" mindset that has actually controlled GCC start-up culture. Founders can now offer partial stakes without setting off an IPO, permitting them to keep functional control while providing liquidity to early financiers and staff members. This mechanism creates a more mature capital ecosystem where business can remain private longer while still fulfilling early capital suppliers.
Both jurisdictions need secondary liquidity infrastructure to draw in global household offices and institutional investors who need flexible exit systems (Source 3: Market Structure Analysis). The development of dedicated secondary trading platforms, or the integration of secondary capabilities into existing exchanges, will be a defining infrastructure story of 2026. For venture funds approaching their maturity horizons, secondary markets represent the difference between returning capital to limited partners on schedule versus seeking extensions.
-- International AI labs are establishing permanent operations in Abu Dhabi and Riyadh, drawn by 2 factors that the GCC possesses in abundance: capital and energy facilities. Large language design training requires both financial resources and industrial-scale computing power, making the Gulf's sovereign wealth funds and energy possessions distinctively attractive to AI developers.
Top AI Development Shifts in Regional Markets
Unlike previous waves of Chinese tech growth that focused on consumer hardware and e-commerce, the current growth targets AI facilities, cloud computing, and smart city contracts. Mid-tier Chinese AI companies, constrained by domestic competition and global sanctions, view the GCC as a neutral market where they can release technology without geopolitical friction.
International AI business developing Gulf operations develop talent pipelines and knowledge transfer mechanisms that regional environments can not reproduce organically. They likewise combine the GCC's position as a 3rd pole in the worldwide AI landscape, unique from Silicon Valley and Beijing (Source 4: Geopolitical Analysis). For local startups, this colonization provides both opportunities and threats.
-- Saudi Arabia and the UAE's capital markets are taken part in direct competitors to become the area's favored exit path for innovation business. This competition, while useful for start-ups in the short-term, develops tactical intricacy for business planning IPOs. Saudi Arabia's Capital Market Authority has implemented reforms developed to minimize listing timelines and disclosure requirements for innovation companies.
Are GCC Enterprises Ready for Applied AI?
IPO readiness has become a tactical concern in both jurisdictions. Unicorns Tabby, Tamara, and Salla are positioned to check public markets in 2026, and their performance will set precedents for the whole ecosystem. If these companies achieve strong public market debuts, they will verify the GCC's capability to support big innovation listings.
The competitors extends to secondary listings and dual-listing structures. Companies are increasingly structuring their corporate entities to preserve optionality between Saudi and UAE exchanges, a flexibility that adds legal and administrative intricacy however takes full advantage of strategic options.-- AI automation will disproportionately impact junior functions consisting of analysts, planners, customer support, and standard coding functions.
Federal governments throughout the GCC accelerated adoption of AI as foundational facilities in 2025, acknowledging that automation is not optional however needed for preserving global competitiveness. This velocity develops a tension between short-term employment objectives and long-lasting productivity imperatives.
Phase three, noticeable on a 3-5 year horizon, will involve basic restructuring of organizational hierarchies as AI lowers the need for middle management layers (Source 6: Labor Economics Analysis). Universities and schools in the GCC face existential pressure to reinvent their curricula. The conventional model of knowledge transmissionlectures, memorization, standardized testingis ending up being obsolete as AI systems can perform these functions more efficiently.
-- Large enterprises in the GCC are transitioning from AI experimentation to full-scale implementation. This shift alters the need dynamics for innovation start-ups, which now find themselves contending versus internal innovation groups at sovereign wealth funds, oil business, and government entities. The business implementation wave develops a bifurcation in the start-up community.

Latest Posts
Recent GCC Tech Innovation Trends
The Best Workflow Tools Analyses in 2026
New Venture Updates From the GCC Startup Sector